Grading Volume Pulled Back in August, But 2026 Is Still Running Hot
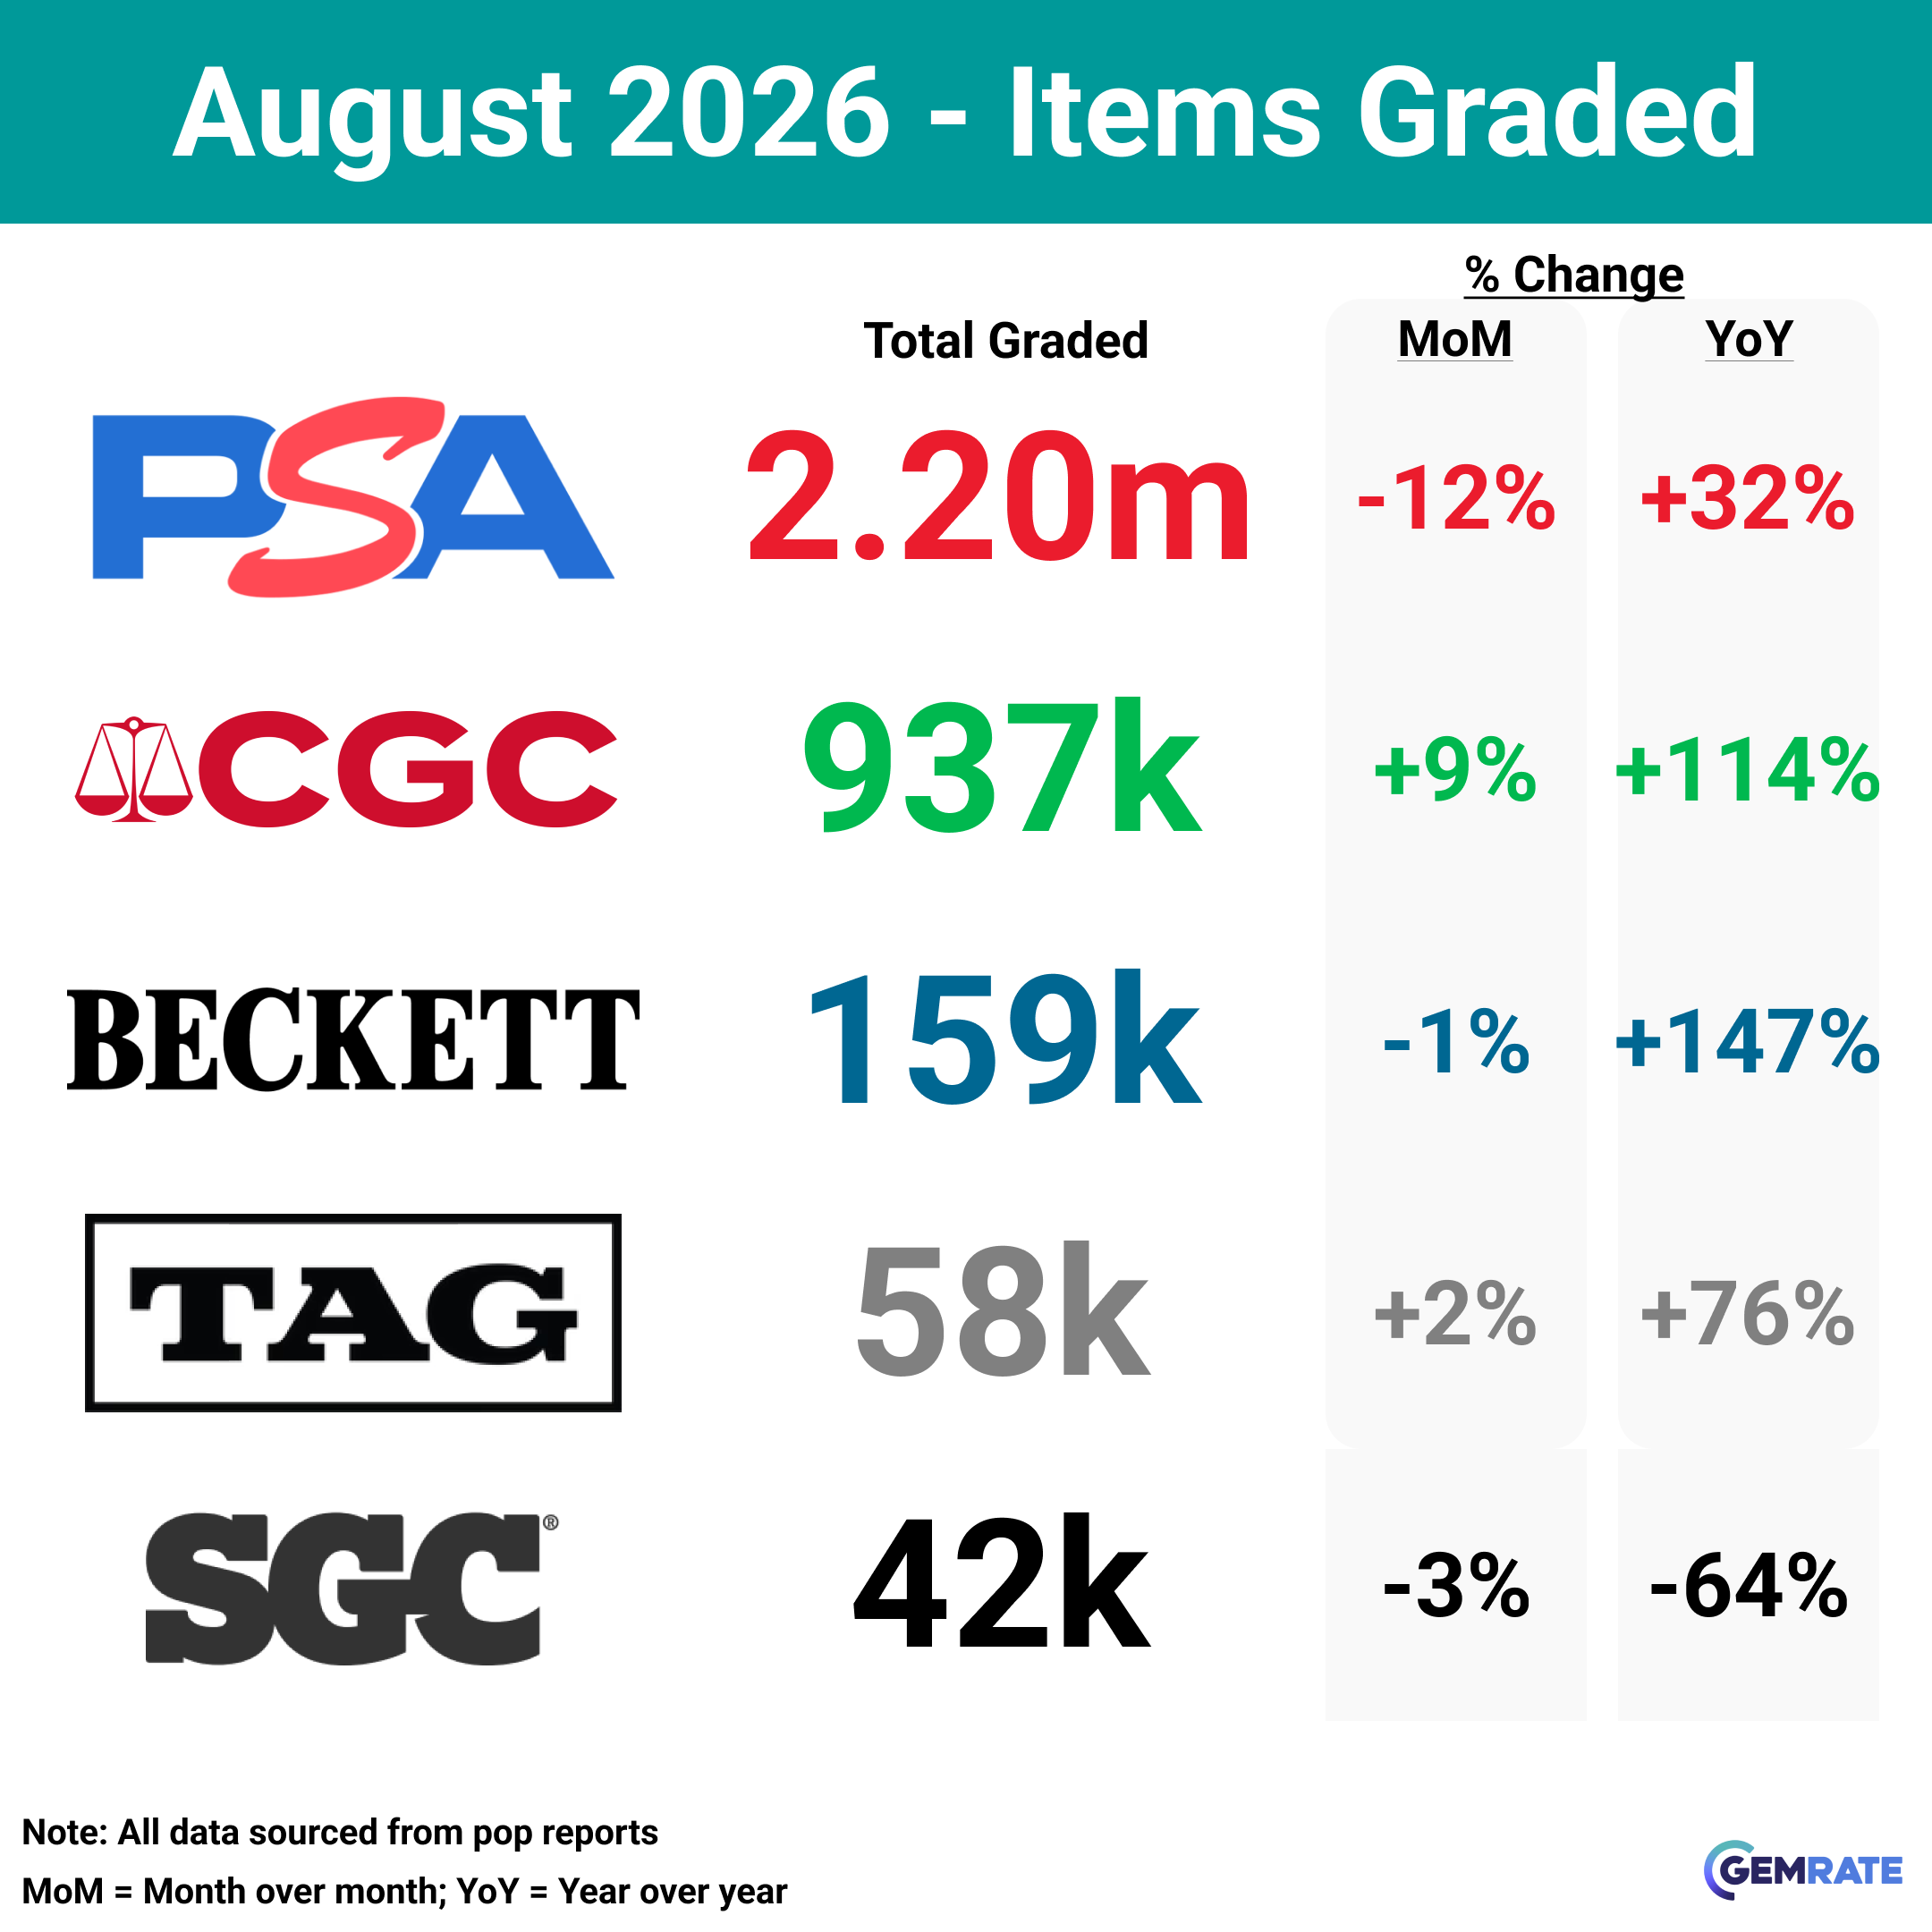
The major grading companies combined for roughly 3.4 million cards in August 2026, down 6% from July's 3.6 million.
A single-month dip after a sustained surge is a normal exhale, not a reversal. The first-half 2026 number — 17.5 million cards, up 23% from the back half of 2025 — tells you where the baseline has moved. Submission backlogs, turnaround times, and graded-card supply on the secondary market all track volume, so collectors watching PSA or CGC turnaround windows or pricing pressure on graded copies should note that the pipeline is still historically full even after August's step back.
- Industry-wide grading volume: ~3.4 million cards in August 2026, down 6% from July.
- July 2026 volume was ~3.6 million cards, itself up 3% from June.
- June 2026 posted a 19% month-over-month volume increase.
- The industry graded ~17.5 million cards in H1 2026, up 23% versus H2 2025.
- May 2026 saw a 5% increase in cards graded per business day versus April.
Grading volume across PSA, CGC, Beckett, and SGC came in at approximately 3.4 million cards in August 2026, a 6% month-over-month decline from July's roughly 3.6 million. The pullback follows a strong run: June posted a 19% monthly jump, May saw a 5% per-business-day increase, and July itself was up 3% from June. Taken together, the industry graded approximately 17.5 million cards in the first half of 2026, a 23% increase over the second half of 2025.
Is the August grading volume decline a sign the hobby is slowing down?
One month of lower volume after four consecutive months of growth is not a trend. The first half of 2026 ran 23% above the second half of 2025, so the industry is operating at a structurally higher level than it was a year ago. August looks like a normal seasonal exhale rather than a reversal.
Which grading companies are included in these figures?
The totals cover PSA, CGC, Beckett, and SGC combined. Individual company breakdowns are not available in this data.
What does higher grading volume mean for turnaround times?
Higher sustained volume generally means more cards in the pipeline, which puts upward pressure on turnaround times. Even with August's dip, the pipeline is still historically large relative to where it was in late 2025.